Solutions From Every Angle 

Environmental Due Diligence for Lenders on Texas commercial properties

Lenders Need Environmental Clarity
Before Money Moves

Commercial lenders carry environmental risk on every deal they finance. If a property securing a loan turns out to be contaminated, the collateral value drops, and in some cases, the lender can inherit liability exposure they never anticipated. Environmental due diligence for lenders isn’t a formality in commercial lending. It’s a fundamental part of responsible underwriting.
All Sides Environmental produces Phase I ESAs compliant with ASTM E1527-21 for developed properties and ASTM E2247-23 for rural land, raw acreage, and farm and ranch tracts, both prepared by a qualified Environmental Professional and structured to satisfy the documentation requirements of banks, credit unions, SBA lenders, and institutional financing sources across Texas.

ASTM E1527 & E2247-23

ASTM Compliant Phase I ESA Standards for Urban and Rural Sites

20+ Years

Environmental Due Diligence Experience

Environmental Due Diligence for Lenders with ASTM compliant Phase I ESA
OUR SERVICES

Our Core Services for Commercial
Lending in Texas

ALL SIDES ENVIRONMENTAL 

Environmental Due Diligence for Lenders property records review
LENDER RISK PROTECTION

What Your Institution Needs
Before the Loan Gets Approved

A thorough, properly scoped Phase I ESA is the most direct way to protect your institution’s financial exposure before a commercial loan closes on a potentially problematic property. Environmental due diligence for lenders serves as a buffer against inheriting the massive costs associated with hazardous waste cleanup.

01

ASTM-Compliant Reports Accepted by Any Lender

Every Phase I meets all ASTM standards, is prepared by a qualified Environmental Professional, and is structured precisely for underwriting review and lender acceptance.

02

Protect Your Collateral from Hidden Liability

Unidentified contamination puts collateral value at risk. Our assessments discover and highlight environmental conditions before your institution’s exposure is locked into a closed loan.

03

Turnaround That Respects Your Deal Timeline

We deliver completed Phase I ESAs within agreed timelines, keeping your borrower’s closing schedule intact and your underwriting team fully informed throughout. Rush jobs available when the schedule allows.

Environmental Due Diligence for Lenders commercial property site inspection
WHY CHOOSE US

Why Texas Lenders
Choose All Sides

Environmental work can feel like a black box when deadlines are tight. We walk you through the scope, keep you updated, and explain what the findings mean for your purchase, refinance, or renovation. You’ll know what we saw, what we tested, and what the next practical options are so you can brief partners and maintain momentum.

EXPLORE MORE

One Point
Contact

You’ll work with the same consultant from kickoff through delivery, with quick callbacks when underwriting or clients have questions.

Transparent
Reports

We organize findings so the key points show up fast, then include the details your lender, attorney, or insurer may request.

Scope Built Around
Your Decision

Every site is different, so we tailor the approach to the property history and your timeline, then explain why each step matters.

Texas Scheduling
You Can Trust

Based in Cypress, Houston, we can move quickly for site visits and keep statewide projects organized with steady updates.

A Track Record of Projects Delivered
on Time & Well Documented

Need an Environmental Report
Before a Commercial Loan Can Close?

We work with lenders and underwriters across Texas to deliver the environmental documentation that deals require. Our reports provide the clarity needed to verify that a property is clean and compliant. Tell us about the property, and we’ll handle the rest.

REQUEST A QUOTE281.770.1360
OUR TESTIMONIALS

Honest Words from Clients Who’ve
Worked with Us

Most commercial lenders require a Phase I Environmental Site Assessment compliant with ASTM E1527-21 or ASTM E2247-23. This must be prepared by a qualified Environmental Professional. If the findings raise concerns about historical contamination, a Phase II Environmental Site Assessment may also be required. We produce both, ensuring the environmental due diligence for lenders is complete and accurate.

A recognized environmental condition (REC) is a finding that indicates contamination may exist on the site due to past or present use. It matters because it directly affects the property’s value and can expose a lender to legal liability. When a REC is identified, most financial institutions require physical testing to confirm the safety of the collateral before the loan proceeds.

CERCLA is a federal law that can hold property owners liable for cleanup costs, even if they didn’t cause the pollution. However, completing a qualifying Phase I ESA before purchase allows a borrower and their lender to claim the “Innocent Landowner Defense.” All of our reports are prepared to the standard that qualifies clients for this critical legal protection.

Yes. SBA programs have specific requirements for environmental due diligence for lenders, requiring reports that meet ASTM E1527-21 or E2247-23 standards. Every report we produce is handled by a qualified Environmental Professional to meet these benchmarks. If SBA financing is involved, we ensure the report follows their specific guidelines from the very beginning.

Yes. Large acreage properties require a specialized standard known as ASTM E2247-23. This is designed specifically for rural land and undeveloped sites where historical use may include agricultural chemicals or old petroleum tanks. We have experience performing these assessments on tracts ranging from small rural lots to several thousand acres across the state.

We notify the lender and relevant parties immediately, explaining exactly what the finding means without using overly technical jargon. A Phase I finding creates a decision point rather than an automatic deal-breaker. We provide the information needed for all parties to decide on the next steps, whether that involves further testing or price negotiations.

Yes. We regularly work with underwriting teams, risk departments, and loan officers. If your institution has specific internal formats or standards that go beyond the basic ASTM requirements, let us know. We prioritize being helpful and direct, making sure the final report works for your specific review team the first time it is delivered.

FAQ’S

Commercial Lending Environmental Questions, Answered

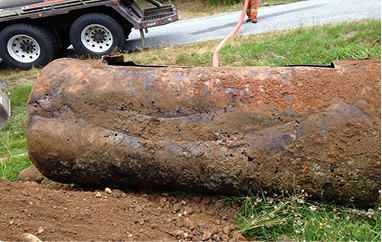
Environmental Due Diligence for Lenders Phase II soil and groundwater testing

Contact Form

What is 6+6?

CONTACT US